Buying your first home is one of the most exciting financial decisions you will ever make, and Southern Indiana is one of the best places in the country to do it. With affordable housing, low property taxes capped at 1% for primary residences, and easy access to Louisville's job market, our region offers first-time buyers an outstanding combination of value and quality of life.
I help first-time buyers in Clark, Floyd, Harrison, and surrounding counties through this process. This guide covers everything you need to know, from getting pre-approved to picking up your keys, with specific programs and resources available right here in Southern Indiana.
Key Takeaways
- Indiana offers down payment assistance through the IHCDA, with income and purchase price limits that vary by county
- You may need less money upfront than you think—FHA loans require just 3.5% down, and USDA loans offer 0% down in eligible rural areas of Southern Indiana
- Typical closing costs in Indiana range from 2-5% of the purchase price
- The entire process from pre-approval to closing typically takes 30-45 days once you find the right home
- Working with a buyer's agent costs you nothing—the seller pays the commission in most transactions
Step 1: Get Your Finances in Order
Before you start browsing listings or attending open houses, you need a clear picture of your financial health. Lenders will evaluate your credit score, debt-to-income ratio, employment history, and savings when determining how much home you can afford.
Check Your Credit Score
Your credit score directly affects your interest rate, which impacts your monthly payment for the life of the loan. Here is a general breakdown:
- 740+: Excellent—qualifies for the best conventional rates
- 700-739: Good—still competitive rates with most lenders
- 620-699: Fair—conventional loans available, but FHA may offer better terms
- 580-619: FHA loans available with 3.5% down
- Below 580: Limited options—consider working on improving your score before applying
You can check your credit for free at AnnualCreditReport.com. If your score needs improvement, even a few months of paying down credit card balances and correcting errors can make a meaningful difference in the rate you receive.
Calculate Your Debt-to-Income Ratio
Lenders use two ratios to determine affordability. The front-end ratio measures your housing costs against gross income (ideally 28% or less). The back-end ratio includes all monthly debts—car payments, student loans, credit cards—plus housing (ideally 36% or less, though FHA allows up to 43-50% in some cases).
Quick math: If your household earns $5,000/month gross, your total housing payment (mortgage, taxes, insurance) should ideally stay below $1,400. With Indiana's low property taxes, your dollars stretch further here than in most states.
Step 2: Get Pre-Approved for a Mortgage
Pre-approval is different from pre-qualification. Pre-qualification is an estimate based on self-reported information. Pre-approval means a lender has verified your income, assets, and credit and is willing to lend you a specific amount. In our market, sellers take pre-approved buyers far more seriously.
I work with several trusted local lenders who understand the Southern Indiana market and can often close faster than national online lenders. Getting pre-approved also helps you set a realistic budget before you fall in love with a home that is outside your range.
Use our mortgage calculators to get an initial estimate of what you can afford before meeting with a lender.
Step 3: Understand Your Loan Options
First-time buyers in Southern Indiana have several loan programs available, each with distinct advantages. The right choice depends on your credit score, down payment savings, military service history, and the location of the home you are purchasing.
| Loan Type | Min. Down Payment | Min. Credit Score | PMI Required? | Best For |
|---|---|---|---|---|
| Conventional | 3-5% | 620 | Yes, if <20% down | Buyers with good credit and savings |
| FHA | 3.5% | 580 | Yes (MIP for life of loan) | Lower credit scores, smaller down payments |
| VA | 0% | No VA minimum* | No | Veterans, active-duty, eligible spouses |
| USDA | 0% | 640 | Guarantee fee (lower than PMI) | Rural areas—many S. Indiana towns qualify |
*Most VA lenders require 580-620 as an overlay minimum
Southern Indiana advantage: Many areas in Harrison, Washington, Scott, and parts of Clark and Floyd counties qualify for USDA loans, which means zero down payment. Towns like Corydon, Salem, Scottsburg, and Charlestown often fall within USDA-eligible boundaries. This is one of the biggest advantages of buying in our region versus Louisville proper.
Step 4: Explore Indiana Down Payment Assistance Programs
One of the most common barriers for first-time buyers is the down payment. The Indiana Housing and Community Development Authority (IHCDA) offers down payment assistance through participating lenders. Our page on Indiana first-time home buyer programs has the details. The short version follows.
IHCDA First Step
First Step is for first-time homebuyers, with exceptions for buyers in targeted areas and buyers with verifiable military status. It provides down payment assistance of 5% of the home price. The assistance is a second mortgage that is not forgiven: it must be repaid in full when the first mortgage ends or the home stops being your primary residence.
- A first-time homebuyer has not had an ownership interest in a principal residence during the three years before closing
- 5% of the home price in down payment assistance
- Must use an IHCDA participating lender
- Income and purchase price limits apply and vary by county
- A homebuyer education certificate is part of the required documents
IHCDA Next Home
Next Home is open to first-time and repeat homebuyers. It provides up to 3.5% of the home price in down payment assistance, also as a second mortgage that is not forgiven.
- Open to first-time and repeat homebuyers
- Up to 3.5% of the home price
- Used with an FHA, Freddie Mac or Fannie Mae 30-year fixed-rate mortgage
- Income and purchase price limits apply
Mortgage credit certificate
Kentucky Housing Corporation offers a Home Buyer Tax Credit, also called a mortgage credit certificate, for income-eligible homebuyers. It is a tax credit based on the mortgage interest you pay. If you are buying in Kentucky, ask a KHC-approved lender whether it applies. Details are on our page on Kentucky first-time home buyer programs.
More programs: Local and county programs can also help with buying costs. Ask your lender, and read our first-time buyers resource page for an overview of the programs in both states.
Step 5: Find the Right Home
Once you are pre-approved and understand your loan options, the fun part begins—house hunting. With a dedicated buyer's agent on your side, you will have access to every listing on the MLS, including properties that may not appear on public websites immediately.
As your agent, I will help you evaluate homes based on more than just the listing photos. We will look at the age and condition of major systems (roof, HVAC, plumbing, electrical), the school district, flood zone status, HOA rules if applicable, and the resale potential of the neighborhood.
Making an Offer
When you find the right home, we will prepare a purchase agreement that includes the offer price, earnest money amount, contingencies, and your proposed closing date. In Southern Indiana, the process is straightforward, but the details matter. A well-structured offer can win out over a higher-priced competing offer if the terms are cleaner.
Earnest Money in Our Market
In Southern Indiana, earnest money deposits typically range from 1% to 3% of the purchase price. On a $250,000 home, that is usually $2,500 to $7,500. The deposit is held in escrow and credited toward your closing costs or down payment at closing. It is not an additional cost—it is part of the money you are already planning to spend.
For a deeper dive into how earnest money works and how to protect your deposit, read our guide: Earnest Money Deposits Explained.
Step 6: The Home Inspection
Never skip the home inspection. Even on new construction, a professional inspector can identify issues that are not visible during a casual walkthrough. In Indiana, a standard home inspection covers the structure, roof, foundation, electrical, plumbing, HVAC, insulation, and more.
What to Expect
- Cost: Typically $350-$500 for a standard single-family home in our area
- Duration: 2-4 hours depending on the size and age of the home
- Attend in person: I strongly recommend being present so the inspector can walk you through findings in real time
- Specialized inspections: Depending on the property, you may also want radon testing ($150-$200), termite/pest inspection ($75-$125), or a sewer scope ($150-$300)
After the inspection, we review the report together and determine which items, if any, to negotiate with the seller. Not every finding is a deal-breaker—the goal is to identify safety hazards, major defects, or expensive repairs that could affect your decision.
Indiana-specific note: Indiana is a "buyer beware" state, meaning sellers are required to complete a Seller's Disclosure form but are not obligated to fix issues. This makes your inspection contingency even more important as a negotiating tool.
Step 7: Understand Closing Costs
Closing costs are the fees and expenses beyond the purchase price that you pay when the transaction is finalized. In Indiana, buyers should expect to pay between 2% and 5% of the purchase price in closing costs.
| Closing Cost Item | Typical Range | Example ($250K Home) |
|---|---|---|
| Loan origination fee | 0.5-1% of loan amount | $1,250-$2,500 |
| Appraisal | $400-$600 | $500 |
| Title insurance & search | $800-$1,500 | $1,100 |
| Home inspection | $350-$500 | $425 |
| Recording fees | $50-$200 | $100 |
| Prepaid taxes & insurance | 2-6 months escrow | $1,500-$3,000 |
| Survey (if required) | $300-$600 | $400 |
| Total estimated | 2-5% of purchase price | $5,000-$12,500 |
Some of these costs can be negotiated. In many transactions, especially when the market favors buyers, sellers may agree to cover a portion of your closing costs as a concession. I negotiate seller concessions regularly for my first-time buyer clients.
For a more detailed breakdown specific to our market, read our guide: Understanding Closing Costs in Indiana and Kentucky.
Step 8: The Timeline from Pre-Approval to Closing
Once your offer is accepted, the clock starts. Here is a typical timeline for a Southern Indiana home purchase:
- Days 1-3: Submit earnest money deposit to escrow
- Days 1-5: Lender orders appraisal; you schedule home inspection
- Days 5-10: Home inspection completed; negotiate any repair requests
- Days 7-14: Appraisal completed and reviewed by lender
- Days 10-25: Loan underwriting—lender verifies all documentation
- Days 20-30: Title search completed; title insurance issued
- Days 25-35: Clear to close—lender issues final approval
- Day 30-45: Closing day—sign documents, transfer funds, receive keys
Pro tip: The number one cause of delayed closings is incomplete documentation. Respond to your lender's requests immediately—every bank statement, tax return, and pay stub they ask for has a purpose. I keep my buyers on track with a closing checklist so nothing falls through the cracks.
Common Mistakes First-Time Buyers Make
The same mistakes come up repeatedly. Avoiding these will save you money, stress, and heartache:
- Making large purchases before closing: Do not buy a car, open new credit cards, or make large furniture purchases before your loan closes. Lenders re-check your credit before funding.
- Changing jobs during the process: Employment changes can delay or derail your loan approval. If a job change is unavoidable, notify your lender immediately.
- Skipping the home inspection: Saving $400 now could cost you $10,000+ in unexpected repairs later.
- Not budgeting for move-in costs: Beyond closing costs, plan for moving expenses, immediate repairs, utility deposits, and basic furnishings.
- Searching without pre-approval: You lose credibility with sellers and risk falling in love with homes outside your budget.
- Ignoring the neighborhood: Visit the area at different times of day and on weekends. Drive the commute to work during rush hour. Talk to neighbors if possible.
Why Southern Indiana Is Ideal for First-Time Buyers
The numbers speak for themselves. Indiana's property tax cap of 1% for primary residences means your tax bill on a $250,000 home will not exceed $2,500 per year—significantly lower than most neighboring states. Combined with a median home price well below the national average and proximity to Louisville's employment base, Southern Indiana offers first-time buyers a genuine opportunity to build wealth through homeownership.
Communities like Jeffersonville, Clarksville, New Albany, Sellersburg, and Charlestown offer growing downtowns and neighborhoods at every price point. Whether you are looking for a starter home under $200,000 or a larger home in the $250,000-$350,000 range, there are options here that simply do not exist across the river in Louisville at the same price.
Ready to Buy Your First Home?
I help first-time buyers navigate this process, and I would love to help you too. Let's talk about your goals, your budget, and the programs that can get you into your home sooner than you think.
Get Your Free Buyer ConsultationFrequently Asked Questions
How much money do I need to buy my first home in Indiana?
FHA loans require at least 3.5% down. IHCDA's First Step program provides 5% of the home price as down payment assistance, which is a second mortgage you repay, and your lender can show you what you would owe at closing. A conventional loan with 3% down on a $200,000 home requires $6,000 for the down payment plus closing costs. VA loans often need no down payment, and USDA loans for homes in eligible rural areas might not need one.
Do I need to take a homebuyer education course?
IHCDA's program guide lists a homebuyer education certificate among the required documents, and it names Fannie Mae's HomeView and Freddie Mac's CreditWise as the only acceptable courses. Ask your lender which course applies to your program. Even if your loan program does not require it, I recommend it.
What is the income limit for IHCDA programs?
Income limits vary by county and household size. IHCDA publishes them on its income and acquisition limits page, and your lender can verify your eligibility against the current guidelines.
Can I buy a home with student loan debt?
Absolutely. Student loans are factored into your debt-to-income ratio, but they do not disqualify you. FHA loans are particularly flexible with student loan debt calculations. Many of my first-time buyer clients have student loans and successfully purchase homes.
How long does the entire homebuying process take?
From your first meeting with a lender to closing day, the entire process typically takes 60-90 days. The house search itself varies—some buyers find their home in a week, others take a few months. Once under contract, closing usually occurs within 30-45 days.
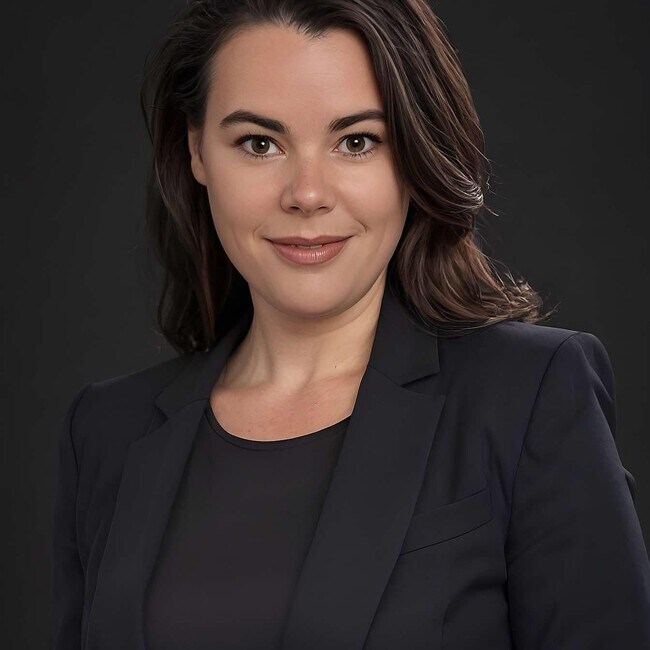
Tina Browning, Realtor®
Serving Southern Indiana and Louisville, Tina specializes in helping first-time buyers, investors, and relocating buyers navigate the Kentuckiana real estate market. Licensed in both Indiana (RB14049944) and Kentucky (240401).